Condo and second-home buyers: warrantability, 10% down, and which rules still apply
Ebook (PDF), $29The Condo Buyer's Mortgage Workbook: Project Approval, HOA Questionnaire and Insurance9 chapters, 41-page PDF, instant access
See what is inside, $29Other titles: All workbooks
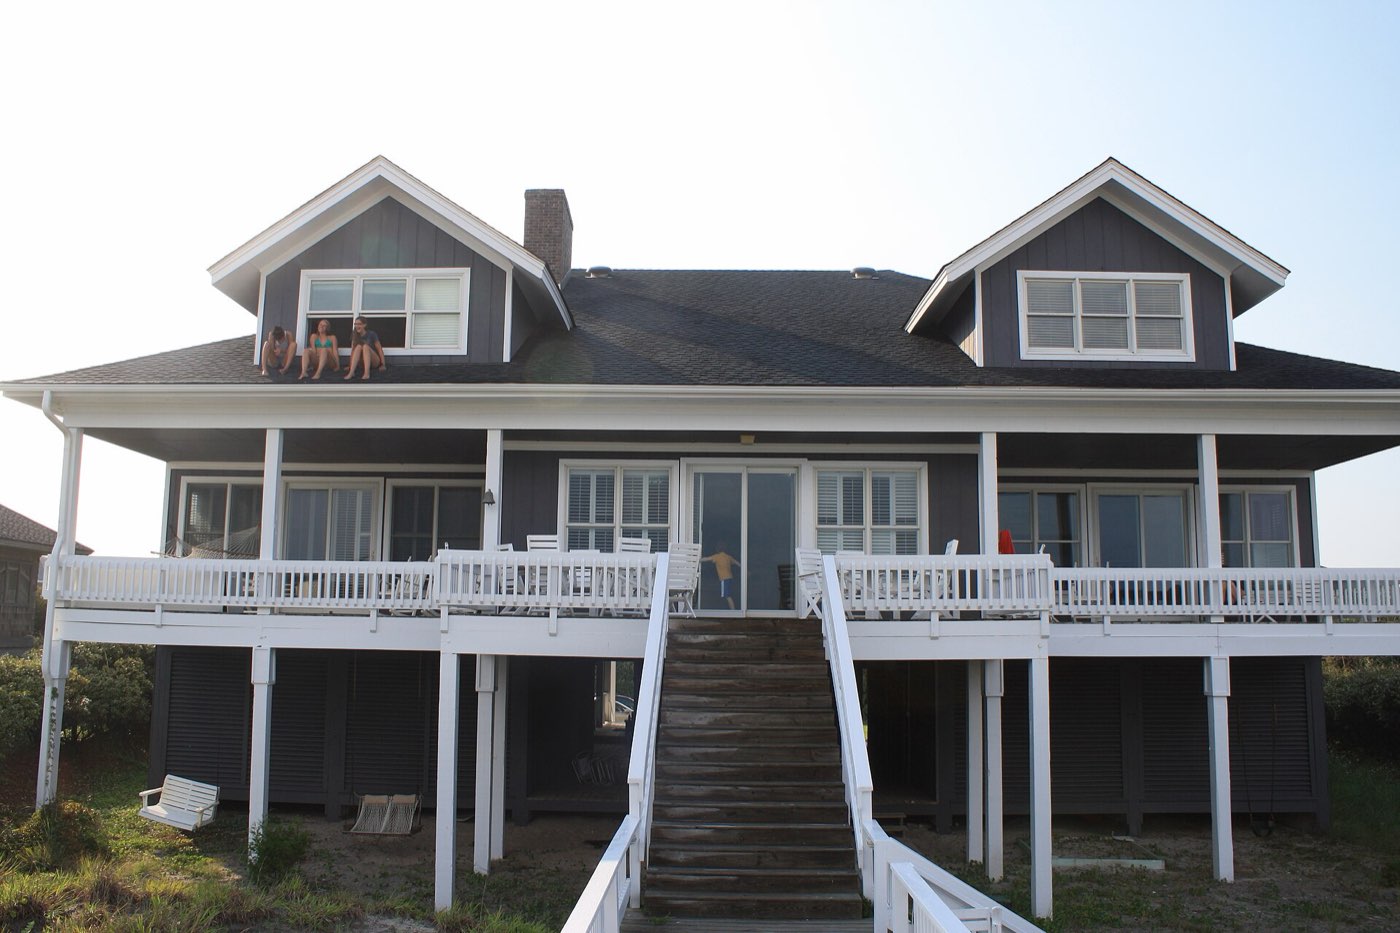
Your credit and income are only half the file: on a condo the building gets underwritten too, and on a second home the occupancy story and the pricing add-ons decide the deal.
Condo units and second homes are underwritten twice: once on you, and once on the property. A condo brings the association’s finances, insurance and litigation into the file; a second home brings an occupancy story the lender has to believe, plus pricing add-ons that do not exist on a primary residence. Neither is exotic, but both fail for reasons that have nothing to do with your credit score.
Who these borrowers are
Three groups land here. Buyers choosing a condo as a primary residence, often in a city where a house is out of reach. Households buying a vacation home — a beach condo, a mountain cabin, a lake house — that they will use part of the year. And retirees or near-retirees buying the place they plan to move into later. The federal rules treat these situations differently: a condo that is your principal dwelling keeps every consumer protection; a second home, even one you love, loses several of them (the three-day right to cancel, HOEPA, the CFPB loss-mitigation timelines, the Homeowners Protection Act), because those rules are written around the principal dwelling.
Loan programs that fit, and why
Conventional loans sold to Fannie Mae or Freddie Mac are the workhorse for both profiles. A second home qualifies with 10% down on a one-unit property, fixed or adjustable, up to the conforming limit; above it, a jumbo lender typically wants 20% to 30% down. Since 2022 the agencies charge loan-level price adjustments (LLPAs) on second homes — roughly 1.125% to 4.125% of the loan amount depending on your down payment on the current grid — which lenders usually convert into a rate somewhere between a quarter and three-quarters of a point higher than a primary residence. FHA and VA loans are for a principal residence only: an FHA or VA condo loan is possible, but only in an approved project (or, for FHA, a unit that passes Single-Unit Approval) and only if you will live there. For a condo the agencies will not buy — a “non-warrantable” project — the options narrow to portfolio and non-QM lenders, usually at 20% to 25% down and a higher rate. See conventional loans for condos and second homes for the product-by-product view.
How the condo itself gets underwritten
The lender runs a project review. For an attached unit in a larger project, Fannie Mae now uses a Full Review (budget, questionnaire, insurance, legal documents), an FHA approval it accepts, or its own PERS review for new and converted projects; Freddie Mac’s Established and New Project reviews mirror this, and both agencies waive the review for detached units and small projects. The short reviews that a bigger down payment used to unlock are gone: Fannie Mae’s Selling Guide of August 5, 2026 no longer lists a Limited Review, and Freddie Mac deleted its Streamlined Review for applications received from August 3, 2026. A project is warrantable when it clears the standard tests: at least 10% of the annual budget going to replacement reserves, no more than 15% of units 60 or more days late on dues, commercial space under 35% of the square footage, no single entity owning more than 20% of the units in a larger project, and no pending litigation about safety, structure or habitability. Since the 2021 Surfside collapse, both agencies also reject projects with significant deferred maintenance, failed inspections, unsafe conditions or special assessments for critical repairs; that policy became permanent in 2023. The HOA’s dues count in your debt-to-income ratio, and a known special assessment is added on top.
To run those tests yourself before the lender does, our condo buyer’s mortgage workbook ($29, PDF) takes the HOA questionnaire line by line with the threshold behind each answer, then the FHA single-unit and VA checks, the master policy against your HO-6, the reserve and special assessment tests, and the condo costs on your Loan Estimate.
How underwriting treats a second home
Occupancy is the whole question. The agencies require that you occupy the home for some part of the year, that it be suitable for year-round use, that you keep exclusive control (no rental pool, no management agreement that decides when it is occupied), and that it is a one-unit dwelling. You may rent it out when you are not there, but projected rental income from the property cannot be used to qualify — you carry the full payment on your own income. Neither agency publishes a minimum distance from your primary residence anymore, but an underwriter will still ask why a unit across town is a “second home”. Expect an occupancy affidavit at closing; claiming second-home status for a unit you intend to rent year-round is occupancy fraud, not a gray area. Reserves are typically two months of the full payment, plus a percentage of the balances on any other financed properties you own. Credit and income are reviewed the same way as on a primary residence; see debt-to-income limits for how the HOA payment and your existing mortgage stack up. On the tax side, IRS Publication 936 explains when second-home interest is deductible; that is a question for a tax professional, not your lender.
Typical pitfalls
- The condo questionnaire comes back late and the project turns out to be non-warrantable — after the appraisal is paid and the rate lock is running.
- A coastal building’s master flood policy is short of replacement cost, and the lender asks for a unit-level flood policy nobody budgeted for.
- The seller discloses a special assessment only at closing; the lender counts it, and the ratio breaks.
- A buyer compares a second-home quote against a friend’s primary-residence rate and concludes the lender is overcharging; the gap is the LLPA.
- Assuming the three-day right to cancel or the 120-day pre-foreclosure rule will apply to the vacation home; neither does.
What to ask a lender
Before paying for anything: which project review this building needs and what it costs; whether they have closed loans in this project recently; how the HOA dues and any pending assessment will be counted; what the second-home LLPA is at your down payment and how it shows up in the rate; whether the loan officer is licensed in the property’s state; and, on the coast, whether the association’s flood coverage satisfies the lender or a gap policy will be required. Ask for the closing cost breakdown with HOA transfer and questionnaire fees shown, not “TBD”. Then compare at least two written quotes — the LLPA is the same everywhere, the margin on top of it is not.
What matters most
- A condo loan is approved on two files: yours and the project’s — budget reserves, delinquencies, litigation, commercial space and, since Surfside, deferred maintenance.
- Second homes need 10% down on a one-unit property and carry agency LLPAs of roughly 1.125% to 4.125% of the loan amount, usually paid through a higher rate.
- FHA and VA finance a condo only as your principal residence and only in an approved project (FHA Single-Unit Approval is the exception route).
- HOA dues count in your debt-to-income ratio; a pending special assessment is added, and projected rental income from a second home is not.
- Several federal protections stop at the principal dwelling: rescission, HOEPA, HPA cancellation rights and the CFPB loss-mitigation timelines do not reach a vacation home.
- On a coastal condo, check the association’s flood policy against replacement cost before you lock — a gap means a unit policy you did not budget.
- Since August 2026 an attached condo in a larger project gets a Full Review whatever the down payment: budget your time and the questionnaire fee, and ask whether the lender has closed in the project before.
Federal rules, read for condo and second-home buyers
- TILA and Regulation Z on a second home: consumer credit, but no three-day right to cancel
- RESPA on a condo or second home: HOA transfer fees, escrow cushions, and the servicing gap
- TRID on a condo or vacation home: questionnaire fees, HOA dues and the tolerance traps
- ECOA on a second home: spousal signatures, retirement income and the appraisal copy rule
- Fair Housing in a condo association: families, 55+ communities and assistance animals
- HMDA data and second homes: the occupancy field, what becomes public, and how to use it
- SAFE Act and a vacation home in another state: check the loan officer’s license there
- ATR/QM on a second home: HOA dues count, projected vacation-rental income does not
- HOEPA and second homes: high-cost protections stop at the principal dwelling
- PMI on a second home: 10% down means MI, and HPA cancellation rights are narrower
- Servicing on a second home: HOA super-liens and the loss-mitigation rules that don’t apply
- FCRA for condo buyers: board screening reports, trigger leads, and the inquiry window
- RCBAP flood insurance: what a condo master policy covers, and the gap a unit buyer insures
- MARS rule for vacation-condo owners: storm assessments, short-sale pitches, advance fees
- SCRA on a second home: the 6% cap and foreclosure stay still apply, VA loans do not
- LO compensation on second-home loans: where LLPAs go and steering toward portfolio loans
Frequently asked questions
Can I buy a second home with less than 10% down?
Not through Fannie Mae or Freddie Mac: a second home is limited to one-unit properties at a maximum 90% loan-to-value, and FHA, VA and USDA are principal-residence programs. Some portfolio lenders advertise lower down payments on vacation homes, usually at a higher rate and with their own occupancy rules. Gift funds may be used toward the 10%, subject to the lender’s documentation requirements.
What makes a condo non-warrantable?
Typical triggers: less than 10% of the budget going to reserves, more than 15% of units 60+ days delinquent on dues, a single owner holding more than 20% of units, commercial space above 35%, pending litigation about safety or structure, a hotel-style rental operation, or significant deferred maintenance and unresolved special assessments for critical repairs. A non-warrantable unit can still be financed, generally through a portfolio lender with more down.
Can I rent out my second home on Airbnb?
Generally yes, as long as you occupy it part of the year, keep exclusive control (no rental pool or management agreement that controls occupancy) and the HOA and local ordinances allow short-term rentals. The projected rental income cannot be used to qualify for the loan, and representing a property you plan to rent full-time as a second home is occupancy misrepresentation.
Why is my second-home rate higher than my primary-residence quote?
Because Fannie Mae and Freddie Mac charge loan-level price adjustments on second homes since April 2022 — on the current grid roughly 1.125% of the loan amount at low loan-to-value, rising to about 4.125% with 10% down. Lenders usually absorb that fee into the rate, which is why the quote lands a fraction of a point above the same loan on a primary residence.
Free 10-page PDF
Free: First-Time Home Buyer Roadmap 2026
First-time buyers who want the steps in the right order, from the first credit report to the keys.
Get the free PDFSources
Related guides: Conventional loans for condos and second homes: the extra rules, Jumbo loans: requirements, rates and how they differ from conforming, Debt-to-income ratio limits by loan type — and how to lower yours, Closing costs for buyers: how much to expect, and what is negotiable.