HELOC vs Cash-Out Refinance: Decision Sheet (2026)
A free printable decision sheet to choose between a HELOC, a home equity loan and a cash-out refinance: your combined loan-to-value, the blended rate with your current first mortgage, a side-by-side cost table and the federal rules that differ.
Free PDF
9 pages, US Letter
411 KB
October 2026 edition
What’s inside
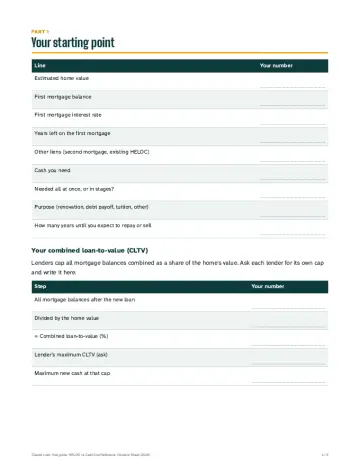
Your starting point and combined loan-to-value
The three tools in one table
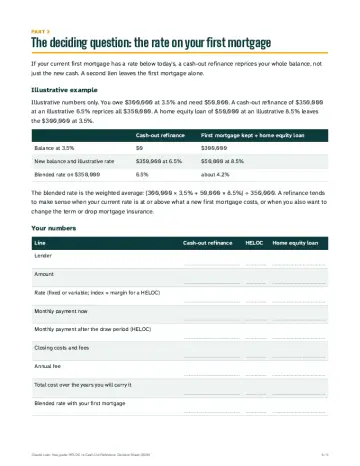
The blended-rate test, with an illustrative example
A side-by-side table for real quotes
Right to cancel, what a HELOC lender may change, cash-out conditions, interest deduction
A decision grid
Who it is for: Homeowners who want to borrow against their equity and have a first mortgage they may or may not want to keep.
HELOC vs Cash-Out Refinance: Decision Sheet (2026): 9 printable pages, free. The download starts as soon as you send the form, and we email you the link.
Next step, optional: get matched with a licensed lender. Your name, email and phone are already filled in: check your situation, state and timeline, then tick the consent box. Nothing is sent to a lender until you do.
Prefer to talk to a licensed lender?
Our guides explain the rules; a loan officer can quote you an actual rate and tell you what you qualify for. Pick your situation and we will pass your request to up to three partner lenders or brokers licensed in your state (check any of them on NMLS Consumer Access). Free, no obligation.
Step 1 of 2: your project
Request received. A partner licensed lender may contact you.
Look inside
Real pages of the PDF, as you will print them.
Page 1 of 9Page 4 of 9Page 6 of 9
Table of contents
How to use this guide, page 3
Part 1: Your starting point, page 4
Part 2: The three tools in one table, page 5
Part 3: The deciding question: the rate on your first mortgage, page 6
Part 4: Rules that differ between the products, page 7
Part 5: Your decision, page 8
Sources and notes, page 9
Frequently asked questions
When is a cash-out refinance cheaper than a HELOC?
Usually when your current first-mortgage rate is at or above today’s rates, or when you also want to change the term or drop mortgage insurance. Otherwise a second lien leaves your cheaper first mortgage untouched. The sheet computes the blended rate on your numbers.
Can a HELOC lender freeze my line?
Under 12 CFR 1026.40(f), a lender may freeze or reduce the line only during periods listed in the rule, for example a significant decline in the home’s value below its appraised value or a material change in your finances.
Can I cancel after signing?
For a HELOC or a refinance with a new lender on your principal home, you generally have until midnight of the third business day to rescind (12 CFR 1026.15 and 1026.23). Purchase loans have no such right.
Is this guide really free, and will a lender call me?
Yes, it is free, with no fees. Only Claude Loan receives your details, to send the guide and answer your question. A lender contacts you only if you tick the separate, optional box asking to be matched.