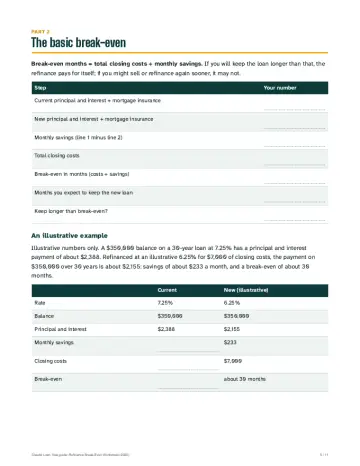
A free printable worksheet that computes your refinance break-even (closing costs divided by monthly savings), compares total cost on the same remaining term, tests a no-closing-cost offer and lists the extra checks for a cash-out refinance.
Free PDF
11 pages, US Letter
419 KB
October 2026 edition
What’s inside
Your current loan and the offer, line by line
The basic break-even, with an illustrative example
The restart-the-clock comparison
No-closing-cost offers: when the higher rate wins
Cash-out checks and your right to cancel
A before-you-sign list
Who it is for: Homeowners with a Loan Estimate for a refinance, or about to ask for one.
Refinance Break-Even Worksheet (2026): 11 printable pages, free. The download starts as soon as you send the form, and we email you the link.
Your guide is ready.Download the Refinance Break-Even Worksheet (PDF), and we have also emailed you the link. You asked to be matched: up to three partner lenders or brokers licensed in your state may contact you.
Next step, optional: get matched with a licensed lender. Your name, email and phone are already filled in: check your situation, state and timeline, then tick the consent box. Nothing is sent to a lender until you do.
Prefer to talk to a licensed lender?
Our guides explain the rules; a loan officer can quote you an actual rate and tell you what you qualify for. Pick your situation and we will pass your request to up to three partner lenders or brokers licensed in your state (check any of them on NMLS Consumer Access). Free, no obligation.
Step 1 of 2: your project
Request received. A partner licensed lender may contact you.
Look inside
Real pages of the PDF, as you will print them.
Page 1 of 11Page 3 of 11Page 5 of 11
Table of contents
How to use this guide, page 3
Part 1: Your current loan and the offer, page 4
Part 2: The basic break-even, page 5
Part 3: Do not restart the clock by accident, page 6
Part 4: No-closing-cost offers, page 7
Part 5: Cash-out refinance: extra checks, page 8
Part 6: Before you sign, page 10
Sources and notes, page 11
Read the guides behind it
The PDF is the printable working copy; these guides explain each rule in depth, free and online.
Divide the total closing costs by the monthly savings on principal, interest and mortgage insurance. If you will keep the new loan longer than that many months, the refinance pays for itself.
Why can a lower payment cost more?
If the new loan restarts a 30-year term, part of the lower payment comes from paying for more years. The worksheet compares total cost on the same remaining term.
Can I cancel a refinance after closing?
For most refinances of your principal home with a new lender, until midnight of the third business day after closing or after the required notice and disclosures, whichever is last (12 CFR 1026.23).
Is this guide really free, and will a lender call me?
Yes, it is free, with no fees. Only Claude Loan receives your details, to send the guide and answer your question. A lender contacts you only if you tick the separate, optional box asking to be matched.