The Mortgage Compliance Study Guide (2026): ECOA, TRID, RESPA, SAFE Act and More
One-page rule summaries with the 2026 thresholds, the deadlines that exam questions love, and more than 100 original practice questions answered with the exact CFR section
Guaranteed as described, or refunded in full, and the wrong title switched within 7 days. Refund policy
For $60 more: The Claude Loan Library: Every Workbook and Ebook, 16 titles, $6.19 per title.
Secure checkout by Stripe (card or Apple Pay). Refund policy
Questions: mail@noreply.claude-loan.com
- 10chapters
- 13tables
Checked before every release
Every rule is cited by section to an official source you can open (how titles are checked, corrections)
- 68automated testsrun at every release: prices, links, pages and data checked before publication.
- ✓Rules cited by sectionevery rule quoted with its section so you can check it.
- October 21, 2026editiondate of the current edition; rules and annual limits are updated when they change, and corrections are dated.
Who it is for
- Bank and credit union employees who must complete or refresh mortgage compliance training (ECOA, TRID, RESPA, flood, SCRA)
- Loan officer candidates who want a cited review of the federal law part of their studies, alongside their NMLS-approved course
- Processors, closers, underwriters and compliance analysts who want the key deadlines and 2026 thresholds in one place
What it is not: it is not an NMLS-approved course and does not count toward pre-licensing or continuing education hours; it is not affiliated with NMLS or any exam provider; it is not legal advice for an institution's compliance program, and it does not reproduce any real exam question.
In pictures
Illustrative photos, published by their authors under free licenses. They do not show our team, our readers or any loan.
Free guides, this ebook or the library
Our free guides explain the rules. The paid titles are the working copies: worksheets and checklists you fill in for your own loan, each citing the official rule.
Free guides
$0
our articles and your free state guide (PDF)
- ✓The rules explained, official sources cited
- —Worksheets you fill in for your own loan
- —13 worksheets and reference tables
- —32-page PDF to print, plus an online copy
- —All 13 ebooks and the complete home loan kit
Compliance study guide
$39
paid once
- ✓The rules explained, official sources cited
- ✓Worksheets you fill in for your own loan
- ✓13 worksheets and reference tables
- ✓32-page PDF to print, plus an online copy
- —All 13 ebooks and the complete home loan kit
The Claude Loan Library: Every Workbook and Ebook
$99
16 titles; $431 bought one by one
- ✓The rules explained, official sources cited
- ✓Worksheets you fill in for your own loan
- ✓13 worksheets and reference tables
- ✓32-page PDF to print, plus an online copy
- ✓All 13 ebooks and the complete home loan kit
Guaranteed as described, or refunded in full
What is inside
- The map of federal mortgage rules and the numbers that move free below
- ECOA and Regulation B
- Regulation Z part 1: TRID disclosures, tolerances, APR and rescission
- Regulation Z part 2: HOEPA, higher-priced loans, ability to repay, QM and loan originator rules
- RESPA and Regulation X: kickbacks, escrow and servicing
- Flood, HPA, SCRA, FCRA, HMDA and fair housing
- The SAFE Act: licensing, registration and loan originator conduct
- Advertising and unfair, deceptive or abusive practices
- Timelines: the deadlines on one page
- Mixed review: 30 questions across all chapters
Included in the paid chapters: 0 checklist items and 10 worksheets or reference tables, each citing the official rule it relies on.
Introduction
Mortgage compliance questions have a recognizable shape: "Which of the following is not accurate regarding…", "Within how many days must…", "To which of the following does ECOA apply…". Behind each one sits a precise rule in the Code of Federal Regulations, a number of days, a dollar threshold updated every January, or a short list of exceptions. Flashcard sites give the answer without the rule, sometimes with an out-of-date number. This guide gives the rule, its section number and its 2026 value, then tests you on it.
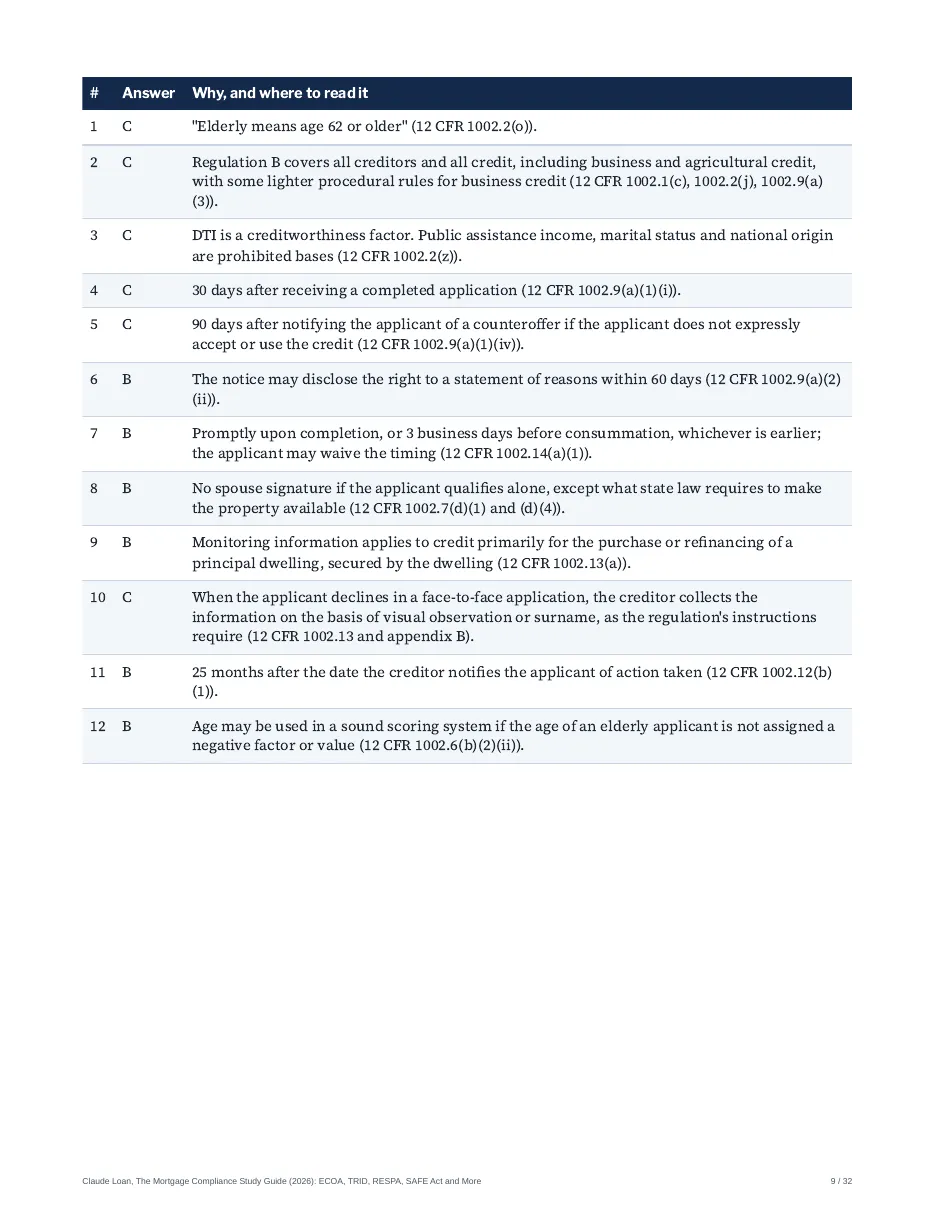
Each chapter covers one law or one family of rules. It opens with a one-page summary, continues with the deadlines and numbers in tables, and ends with original practice questions followed by an answer key that explains why each answer is right and cites the section to read. The questions are written by us to practice the rules; they are not taken from any real exam.
How to use it: read the summary, close the guide, answer the questions on paper, then check the key and reread the cited section for every mistake. Chapter 9 puts every deadline on one page and chapter 10 is a mixed review across all chapters. The "numbers that move" table in chapter 1 lists the thresholds that change every year: check it again each January.
The rules quoted are those in force in October 2026, read on the eCFR: Regulation B (12 CFR part 1002), Regulation X (12 CFR part 1024), Regulation Z (12 CFR part 1026) and its official commentary, the SAFE Act rules (12 CFR parts 1007 and 1008), the federal flood rules (12 CFR part 339 and its counterparts), and the statutes cited in each chapter. The 2026 Regulation Z thresholds come from the CFPB's final rule published in the Federal Register on December 15, 2025 (90 FR, document 2025-22773).
Chapter 1: The map of federal mortgage rules and the numbers that move
Who writes and who enforces
| Law | Regulation | Rule-writer | What it governs |
|---|---|---|---|
| Equal Credit Opportunity Act (ECOA) | Regulation B, 12 CFR part 1002 | CFPB | Discrimination in any credit, notices of action taken, appraisal copies |
| Truth in Lending Act (TILA) | Regulation Z, 12 CFR part 1026 | CFPB | Disclosures (TRID), APR, rescission, HOEPA, higher-priced loans, ability to repay, loan originator compensation and qualification |
| Real Estate Settlement Procedures Act (RESPA) | Regulation X, 12 CFR part 1024 | CFPB | Kickbacks, affiliated businesses, escrow accounts, servicing |
| Home Mortgage Disclosure Act (HMDA) | Regulation C, 12 CFR part 1003 | CFPB | Reporting of mortgage application data |
| SAFE Act | 12 CFR part 1007 (federal registration) and part 1008 (state licensing) | CFPB | Loan originator licensing and registration |
| Fair Housing Act | 24 CFR part 100 | HUD | Discrimination in housing and residential real estate transactions |
| Flood Disaster Protection Act | 12 CFR part 339 (FDIC) and equivalent rules of the other banking agencies | Banking agencies | Flood insurance on loans in special flood hazard areas |
| Homeowners Protection Act (HPA) | Statute, 12 U.S.C. 4901 and following | (statute) | Private mortgage insurance cancellation and termination |
| Servicemembers Civil Relief Act (SCRA) | Statute, 50 U.S.C. 3901 and following | (statute) | Interest rate cap and foreclosure protections for servicemembers |
| Fair Credit Reporting Act (FCRA) | Regulation V, 12 CFR part 1022 | CFPB | Credit reports, risk-based pricing and credit score disclosures |
The numbers that move every year (2026 values)
| Threshold | 2026 value | Rule |
|---|---|---|
| HOEPA high-cost: points and fees trigger for loans of $27,592 or more | 5% of the total loan amount | 12 CFR 1026.32(a)(1)(ii) as adjusted |
| HOEPA high-cost: points and fees trigger for smaller loans | Lesser of 8% of the total loan amount or $1,380 | Same |
| General QM price-based limit, first lien, loan of $137,958 or more | APR at least 2.25 points over APOR fails | 12 CFR 1026.43(e)(2)(vi) as adjusted |
| General QM, first lien, $82,775 to less than $137,958 | 3.5 points | Same |
| General QM, first lien, less than $82,775 | 6.5 points | Same |
| QM points and fees cap, loan of $137,958 or more | 3% of the total loan amount | 12 CFR 1026.43(e)(3) as adjusted |
| QM points and fees cap, $82,775 to less than $137,958 | $4,139 | Same |
| QM points and fees cap, $27,592 to less than $82,775 | 5% | Same |
| QM points and fees cap, $17,245 to less than $27,592 | $1,380 | Same |
| QM points and fees cap, less than $17,245 | 8% | Same |
| Conforming loan limit, one unit, baseline | $832,750 | FHFA, 2026 |
| FHA forward mortgage ceiling and HECM maximum claim amount | $1,249,125 | HUD Mortgagee Letters 2025-23 and 2025-22 |
Source for the Regulation Z values: CFPB final rule, Federal Register of December 15, 2025 (2025-22773).
The numbers that do not move
| Rule | Value | Section |
|---|---|---|
| "Elderly" under Regulation B | 62 or older | 12 CFR 1002.2(o) |
| Notice of action taken on a completed application | 30 days | 12 CFR 1002.9(a)(1)(i) |
| Appraisal copy | Promptly upon completion or 3 business days before consummation, whichever is earlier | 12 CFR 1002.14(a)(1) |
| Regulation B record retention | 25 months (12 months for business credit) | 12 CFR 1002.12(b) |
| Loan Estimate delivery | Within 3 business days after application | 12 CFR 1026.19(e)(1)(iii) |
| Waiting period after the Loan Estimate | 7 business days before consummation | 12 CFR 1026.19(e)(1)(iii)(B) |
| Closing Disclosure receipt | At least 3 business days before consummation | 12 CFR 1026.19(f)(1)(ii)(A) |
| Right of rescission | 3 business days; extended up to 3 years if notices or material disclosures are missing | 12 CFR 1026.23(a) |
| Higher-priced mortgage loan, first lien, conforming size | APR 1.5 points or more over APOR | 12 CFR 1026.35(a)(1)(i) |
| Escrow cushion | No more than one-sixth of estimated annual disbursements | 12 CFR 1024.17(c)(1) |
| Servicing transfer notice | At least 15 days before (transferor) and no more than 15 days after (transferee) | 12 CFR 1024.33(b)(3) |
| Notice of error and information request acknowledgment | 5 business days | 12 CFR 1024.35(d), 1024.36(c) |
| Response to notice of error or information request | 30 business days, extendable by 15 | 12 CFR 1024.35(e), 1024.36(d) |
| Early intervention live contact | By the 36th day of delinquency | 12 CFR 1024.39(a) |
| First foreclosure filing | Not before the loan is more than 120 days delinquent | 12 CFR 1024.41(f)(1) |
| SAFE Act pre-licensing education | 20 hours (3 federal law, 3 ethics, 2 nontraditional, the rest elective) | 12 CFR 1008.105(d) |
| SAFE Act continuing education | 8 hours a year (3 federal law, 2 ethics, 2 nontraditional) | 12 CFR 1008.107(a)(2) |
| SAFE Act test passing score | 75% | 12 CFR 1008.105(e) |
Checkout by Stripe
Pay by card on Stripe’s secure page. Your card details never reach our servers.
Instant access
Your ebook opens right after payment, to bookmark, print or save as a PDF. A payment receipt is emailed to you.
One price, paid once
The price shown is the total in US dollars. No subscription, nothing charged later. Refund policy.
Sources you can check
An information publisher, not a lender, broker or advisor; not legal or financial advice. Terms of sale.
Frequently asked questions
What exactly do I receive?
Right after payment you land on your ebook page: the full text online, and a button to download the PDF (32 pages, US Letter, printable). Bookmark the page: the link stays valid and always shows the latest version. Your invoice is emailed to you.
Is it up to date for 2026?
Yes. Every rule is quoted as in force in October 2026, with its section number (CFR, HUD, FEMA, Fannie Mae or state rule) so you can check it yourself. When a rule or an annual limit changes, we update the online copy and the PDF.
Is the payment secure, and is it a subscription?
You pay once on Stripe’s secure checkout, by card or Apple Pay; your card details go to Stripe and never reach us. There is no subscription and nothing is charged later.
Who publishes the ebook?
Claude Loan, an information publisher: not a lender, broker, insurance agent, law firm or advisor, with no NMLS license. The ebook explains the official rules and gives you worksheets; your lender, insurance agent, a HUD-approved housing counselor or an attorney give the answers that apply to you.
What is the guarantee?
The ebook is guaranteed as described: if it does not open or contains an error, we fix it, and if we cannot, we refund you in full. Bought the wrong title by mistake? Write within 7 days and we switch it. A duplicate payment is always refunded. See the refund policy in the terms of sale.
Our other ebooks
Flood insurance ebook
The Flood Insurance Workbook for Home Buyers and Condo Owners (2026)
What your lender must require, what an NFIP or private policy really pays, the condo RCBAP gaps, and how to lower the premium before you sign.
$19 9 chapters, 28-page PDF + online copy
Title insurance ebook
The Owner's Title Insurance Guide for Home Buyers (2026)
Decide on the owner’s policy with real numbers: state rates, the Loan Estimate math, who pays, the commitment line by line, endorsements and claims.
$19 8 chapters, 22-page PDF + online copy
Construction loan ebook
The Construction and Renovation Loan Workbook (2026)
One-time or two-time close, FHA 203(k) 2026 rules, HomeStyle, USDA combination loans, then budgets, builder checks, draw schedules and conversion.
$24 10 chapters, 27-page PDF + online copy
Reverse mortgage ebook
The Reverse Mortgage (HECM) Decision Workbook (2026)
The 2026 HECM limit, every fee, payout choices, the rules that protect a spouse and heirs, counseling preparation and the alternatives, priced.
$24 10 chapters, 24-page PDF + online copy
Self-employed ebook
The Self-Employed Mortgage Income Workbook (2026)
Run the Form 1084 cash flow on your own returns: Schedule C, K-1s, S corps, the liquidity test, under two years, declining income and business funds.
$24 11 chapters, 34-page PDF + online copy
SCRA ebook
The SCRA and Military Homeowner Workbook (2026)
Claim the 6% cap, stop a foreclosure without a court order, end a lease on orders, then keep, rent or sell the house after a PCS, with letters and trackers.
$19 10 chapters, 31-page PDF + online copy
Low appraisal ebook
The Low Appraisal and Appraisal Gap Playbook (2026)
Read the appraisal like an underwriter, file a reconsideration of value that gets read, and close an appraisal gap with numbers, not panic.
$19 10 chapters, 28-page PDF + online copy
Jumbo loan ebook
The Jumbo and High-Balance Loan Workbook (2026)
Find your county’s 2026 limit, see what changes between standard, high-balance and jumbo loans, and price staying under the line with your own numbers.
$29 8 chapters, 28-page PDF + online copy
LO compensation handbook
The Loan Originator Compensation and Conduct Handbook (12 CFR 1026.36, 2026)
Audit a pay plan against 12 CFR 1026.36: lender-paid or borrower-paid, the proxy test, the 10% bonus limit, the steering safe harbor, NMLS IDs and records.
$49 10 chapters, 41-page PDF + online copy
Flood compliance toolkit
The Flood Compliance Toolkit for Lenders and Loan Staff (12 CFR 339, 2026)
Test a flood file against 12 CFR 339 and the 2022 Interagency Q&As: triggers, the determination, exemptions, the minimum amount, deductibles, escrow, notices, private flood and force placement.
$39 9 chapters, 35-page PDF + online copy
Condo buyer ebook
The Condo Buyer's Mortgage Workbook: Project Approval, HOA Questionnaire and Insurance
Know before the appraisal whether the building can be financed: the 2026 project review rules, the HOA questionnaire line by line, FHA and VA approval, HO-6, assessments and the true monthly cost.
$29 9 chapters, 41-page PDF + online copy
ECOA adverse action toolkit
The ECOA and Regulation B Adverse Action Toolkit for Mortgage Lenders (2026)
Send the right Regulation B notice on time with the real reasons: applications, the 30-day clock, Appendix C forms, counteroffers, the valuations rule, age and income, 25-month records.
$49 10 chapters, 50-page PDF + online copy
$39 is the total you pay: no tax or fee is added at checkout. Payment by Stripe (card or Apple Pay), instant access after payment. Terms of sale and refund policy. Claude Loan is an information publisher, not a lender or advisor; the ebook is not legal or financial advice.