The SCRA and Military Homeowner Workbook (2026)
Use the Servicemembers Civil Relief Act on your mortgage, your debts and your lease, then make the housing decisions that come with orders: buy with a VA loan, keep and rent, or sell, with letters, trackers and a calendar
Guaranteed as described, or refunded in full, and the wrong title switched within 7 days. Refund policy
For $80 more: The Claude Loan Library: Every Workbook and Ebook, 16 titles, $6.19 per title.
Secure checkout by Stripe (card or Apple Pay). Refund policy
Questions: mail@noreply.claude-loan.com
- 10chapters
- 5letter templates
- 37checklist items
- 17tables
- 9links to official sources
Checked before every release
Every rule is cited by section to an official source you can open (how titles are checked, corrections)
- 68automated testsrun at every release: prices, links, pages and data checked before publication.
- 9official sources linkedevery rule quoted with its section (CFPB, VA, HUD) so you can check it.
- October 23, 2026editiondate of the current edition; rules and annual limits are updated when they change, and corrections are dated.
Built from the rules and data of federal law (eCFR, U.S. Code), CFPB, HUD, VA.
Who it is for
- Active-duty service members, and Guard or Reserve members called to active duty, who carry a mortgage, a car loan, credit cards or private student loans taken out before service
- Military spouses who manage the household paperwork, the mortgage and the lease while the service member is away
- Service members with PCS or deployment orders who must decide whether to keep, rent or sell the house, or who want to buy with a VA loan at the next duty station
What it is not: it is not legal advice on your own case: a military legal assistance office gives that for free, and the workbook tells you what to bring; it is not a VA loan qualification guide (income, residual income, credit): that is covered in our FHA, VA and USDA program workbook.
In pictures
Illustrative photos, published by their authors under free licenses. They do not show our team, our readers or any loan.
Free guides, this ebook or the library
Our free guides explain the rules. The paid titles are the working copies: worksheets and checklists you fill in for your own loan, each citing the official rule.
Free guides
$0
our articles and your free state guide (PDF)
- ✓The rules explained, official sources cited
- —Worksheets you fill in for your own loan
- —37 checklist items
- —17 worksheets and reference tables
- —31-page PDF to print, plus an online copy
- —All 13 ebooks and the complete home loan kit
SCRA ebook
$19
paid once
- ✓The rules explained, official sources cited
- ✓Worksheets you fill in for your own loan
- ✓37 checklist items
- ✓17 worksheets and reference tables
- ✓31-page PDF to print, plus an online copy
- —All 13 ebooks and the complete home loan kit
The Claude Loan Library: Every Workbook and Ebook
$99
16 titles; $431 bought one by one
- ✓The rules explained, official sources cited
- ✓Worksheets you fill in for your own loan
- ✓37 checklist items
- ✓17 worksheets and reference tables
- ✓31-page PDF to print, plus an online copy
- ✓All 13 ebooks and the complete home loan kit
Guaranteed as described, or refunded in full
What is inside
- Who the SCRA protects, and for how long free below
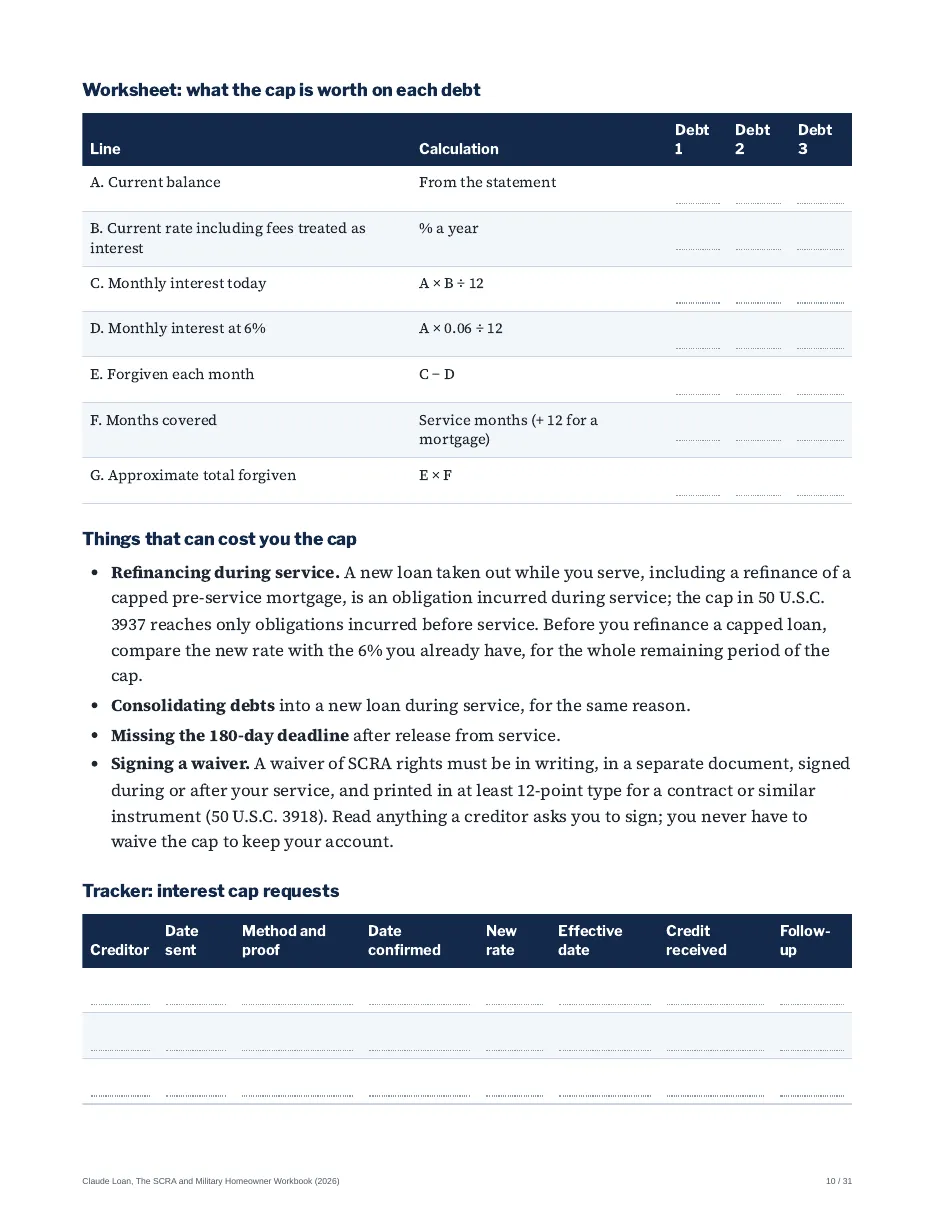
- The 6% interest cap: request it, check it, keep it
- The house when payments get hard: foreclosure, courts and your servicer
- Renting: ending a lease and the eviction rule
- Taxes and the house
- Buying with a VA loan while you serve
- PCS orders: keep and rent the house, or sell it
- Deployment: powers of attorney and the paperwork that keeps running
- When a creditor or landlord gets it wrong
- Your calendar and final checklists
- Sources
Included in the paid chapters: 37 checklist items and 12 worksheets or reference tables, each citing the official rule it relies on.
Introduction
Orders change everything at once. A move across the country or a deployment overseas lands on a household that already has a mortgage, a lease, a car loan and a few credit cards, and every one of those contracts was written for a civilian who stays put. Congress wrote the Servicemembers Civil Relief Act (SCRA) for exactly that moment. It caps the interest on debts you took on before service, stops a foreclosure without a court order, protects you in court cases you cannot attend, and lets you end a lease when orders come. None of it is automatic in practice: most protections start with a letter from you and a copy of your orders, and some have deadlines that run out quietly after you leave service.
This workbook turns the law into a set of moves. Chapter 1 sets out who is protected and for how long, protection by protection, so you know which ones apply to you today and which will still apply after you separate. Chapter 2 is the 6% interest cap: what counts as interest, the letter to send, how to check that the creditor applied it correctly. Chapter 3 covers the house when payments get hard: foreclosure, default judgments and the notices your servicer must send. Chapter 4 is for renters. Chapter 5 deals with state taxes and the house. Chapters 6 to 8 are the housing decisions that come with military life: buying with a VA loan while serving, keeping and renting the house or selling it after a PCS, and the paperwork that keeps everything running during a deployment. Chapter 9 explains what to do when a creditor or landlord gets it wrong. Chapter 10 holds the calendar and the final checklists.
How to use it: fill in the service record and debt list in chapter 1 the day you receive orders, then work through the chapters that match your situation. Every letter in this workbook is a model you adapt; keep a copy of everything you send and the proof of delivery.
The rules quoted are those in force in October 2026: the Servicemembers Civil Relief Act (50 U.S.C. 3901 and following, as published by the Office of the Law Revision Counsel), the VA home loan statutes (38 U.S.C. 3704 and 3710) and VA's published funding fee and entitlement rules on VA.gov, the Military Lending Act (10 U.S.C. 987) and the military power of attorney statute (10 U.S.C. 1044b). Section numbers are given so you can read the official text.
Chapter 1: Who the SCRA protects, and for how long
The SCRA protects "servicemembers" during their "period of military service", and for some protections, for a set time after it ends. Getting these two definitions right answers most of the questions people search for, including whether the law applies to veterans and to personal loans.
Who counts as being in military service
Military service, for the SCRA (50 U.S.C. 3911), means:
| Who | What counts as military service |
|---|---|
| Army, Navy, Air Force, Marine Corps, Space Force, Coast Guard | Active duty, as defined in 10 U.S.C. 101(d)(1) |
| National Guard | Title 10 active duty; also a call to active service for more than 30 consecutive days under 32 U.S.C. 502(f), authorized by the President or the Secretary of Defense to respond to a national emergency declared by the President and supported by federal funds |
| Commissioned officers of the Public Health Service and NOAA | Active service |
| Any of the above | Periods of absence from duty for sickness, wounds, leave or other lawful cause |
The period of military service runs from the date you enter military service to the date you are released from it (or die while in it). Two groups are protected even before they report (50 U.S.C. 3917): a member of a reserve component who receives an order to report for military service, and a person ordered to report for induction. For them, the protections of the general, judicial and financial parts of the Act (including the interest cap and the foreclosure rule) start on the date the order is received.
National Guard members on ordinary state active duty, or on Title 32 duty that does not meet the conditions above, are not in "military service" for the federal SCRA. Many states have their own laws for Guard members on state orders; ask your state's Guard legal office.
Spouses and dependents
A dependent, for the SCRA, is your spouse, your child (as defined in 38 U.S.C. 101(4)), or a person to whom you gave more than half of their support during the 180 days before an application for relief (50 U.S.C. 3911). Several protections reach them directly:
- the interest cap covers debts you took on jointly with your spouse before service (50 U.S.C. 3937);
- the eviction protection covers premises occupied by you or your dependents (50 U.S.C. 3951);
- ending a lease under the Act also ends a dependent's obligation under that joint lease (50 U.S.C. 3955);
- the tax residence rules protect a spouse who moves to be with you under your orders (50 U.S.C. 4001).
A debt in your spouse's name alone, taken out without you, is not covered by the interest cap.
Does the SCRA apply to veterans?
Not as such. The protections attach to the period of military service, and most end when it ends. A few run for a fixed time after you leave service, and those windows matter at separation and retirement:
| Protection | During service | After release from service | Source |
|---|---|---|---|
| 6% cap on a pre-service mortgage | Yes | One more year | 50 U.S.C. 3937(a) |
| 6% cap on other pre-service debts (cards, car, personal and student loans) | Yes | No | 50 U.S.C. 3937(a) |
| Deadline to ask for the cap | 180 days after the end of service | 50 U.S.C. 3937(b) | |
| No foreclosure sale without a court order (pre-service mortgage) | Yes | One more year | 50 U.S.C. 3953 |
| Court stay of a mortgage enforcement suit | Yes | Suits filed within one year after | 50 U.S.C. 3953 |
| Reopening a default judgment | Judgment entered during service or within 60 days after | Apply within 90 days after | 50 U.S.C. 3931(g) |
| Stay of a civil case you know about | Yes | Within 90 days after | 50 U.S.C. 3932 |
| Sale of property for unpaid taxes only by court order; redemption | Yes | Court stay and redemption up to 180 days after | 50 U.S.C. 3991 |
| Eviction only by court order | Yes | No | 50 U.S.C. 3951 |
A veteran who is not in one of these windows relies on other laws: VA home loan benefits, the protections every borrower has under federal mortgage servicing rules, and state law. The VA's Legal Services for Veterans program and the VA Office of General Counsel list free legal help for veterans.
Does it apply to personal loans?
Yes, if the loan was taken out before you entered military service. The interest cap applies to any "obligation or liability" that bears interest above 6% a year and that you incurred, alone or jointly with your spouse, before service (50 U.S.C. 3937). That includes personal loans, credit cards, car loans, private student loans and mortgages. It does not reach debts you took on during service. For credit taken during active duty, a different law, the Military Lending Act, caps most consumer credit at a 36% annual percentage rate; it expressly excludes residential mortgages (10 U.S.C. 987).
Every creditor, every lender
The SCRA is a federal statute. It binds every bank, credit union, servicer, landlord and court in the United States, whatever its size or its own policy. Some creditors go further than the law (a lower cap, applying it to debts taken during service, a longer window); that is their choice and worth asking about, but it is never a condition of your legal rights.
Worksheet: your service record
| Item | Your answer |
|---|---|
| Branch and component (active, Guard, Reserve) | |
| Date orders were received | |
| Date you entered (or will enter) military service | |
| Type of orders (PCS, deployment of 90 days or more, activation, other) | |
| Expected end of this period of service, if known | |
| Date one year after the end of service (mortgage cap and foreclosure window) | |
| Date 180 days after the end of service (last day to ask for the cap) | |
| Where your orders and your DD Form 214 (at separation) are stored |
Worksheet: your debt list
List every debt and lease. The "taken before service?" column decides most of what follows.
| Creditor or landlord | Type | Taken before service? (date) | In whose name | Current rate | Above 6%? | Chapter |
|---|---|---|---|---|---|---|
| Mortgage | 2, 3 | |||||
| Car loan or lease | 2, 4 | |||||
| Credit card | 2 | |||||
| Personal or student loan | 2 | |||||
| Residential lease | 4 | |||||
Checkout by Stripe
Pay by card on Stripe’s secure page. Your card details never reach our servers.
Instant access
Your ebook opens right after payment, to bookmark, print or save as a PDF. A payment receipt is emailed to you.
One price, paid once
The price shown is the total in US dollars. No subscription, nothing charged later. Refund policy.
Sources you can check
9 links to official sources (CFPB, VA, HUD, U.S. Code). An information publisher, not a lender, broker or advisor; not legal or financial advice. Terms of sale.
Frequently asked questions
What exactly do I receive?
Right after payment you land on your ebook page: the full text online, and a button to download the PDF (31 pages, US Letter, printable). Bookmark the page: the link stays valid and always shows the latest version. Your invoice is emailed to you.
Is it up to date for 2026?
Yes. Every rule is quoted as in force in October 2026, with its section number (CFR, HUD, FEMA, Fannie Mae or state rule) so you can check it yourself. When a rule or an annual limit changes, we update the online copy and the PDF.
Is the payment secure, and is it a subscription?
You pay once on Stripe’s secure checkout, by card or Apple Pay; your card details go to Stripe and never reach us. There is no subscription and nothing is charged later.
Who publishes the ebook?
Claude Loan, an information publisher: not a lender, broker, insurance agent, law firm or advisor, with no NMLS license. The ebook explains the official rules and gives you worksheets; your lender, insurance agent, a HUD-approved housing counselor or an attorney give the answers that apply to you.
What is the guarantee?
The ebook is guaranteed as described: if it does not open or contains an error, we fix it, and if we cannot, we refund you in full. Bought the wrong title by mistake? Write within 7 days and we switch it. A duplicate payment is always refunded. See the refund policy in the terms of sale.
Our other ebooks
Flood insurance ebook
The Flood Insurance Workbook for Home Buyers and Condo Owners (2026)
What your lender must require, what an NFIP or private policy really pays, the condo RCBAP gaps, and how to lower the premium before you sign.
$19 9 chapters, 28-page PDF + online copy
Title insurance ebook
The Owner's Title Insurance Guide for Home Buyers (2026)
Decide on the owner’s policy with real numbers: state rates, the Loan Estimate math, who pays, the commitment line by line, endorsements and claims.
$19 8 chapters, 22-page PDF + online copy
Construction loan ebook
The Construction and Renovation Loan Workbook (2026)
One-time or two-time close, FHA 203(k) 2026 rules, HomeStyle, USDA combination loans, then budgets, builder checks, draw schedules and conversion.
$24 10 chapters, 27-page PDF + online copy
Reverse mortgage ebook
The Reverse Mortgage (HECM) Decision Workbook (2026)
The 2026 HECM limit, every fee, payout choices, the rules that protect a spouse and heirs, counseling preparation and the alternatives, priced.
$24 10 chapters, 24-page PDF + online copy
Compliance study guide
The Mortgage Compliance Study Guide (2026): ECOA, TRID, RESPA, SAFE Act and More
One-page rule summaries with the 2026 thresholds and more than 100 original practice questions, each answered with the exact CFR section.
$39 10 chapters, 32-page PDF + online copy
Self-employed ebook
The Self-Employed Mortgage Income Workbook (2026)
Run the Form 1084 cash flow on your own returns: Schedule C, K-1s, S corps, the liquidity test, under two years, declining income and business funds.
$24 11 chapters, 34-page PDF + online copy
Low appraisal ebook
The Low Appraisal and Appraisal Gap Playbook (2026)
Read the appraisal like an underwriter, file a reconsideration of value that gets read, and close an appraisal gap with numbers, not panic.
$19 10 chapters, 28-page PDF + online copy
Jumbo loan ebook
The Jumbo and High-Balance Loan Workbook (2026)
Find your county’s 2026 limit, see what changes between standard, high-balance and jumbo loans, and price staying under the line with your own numbers.
$29 8 chapters, 28-page PDF + online copy
LO compensation handbook
The Loan Originator Compensation and Conduct Handbook (12 CFR 1026.36, 2026)
Audit a pay plan against 12 CFR 1026.36: lender-paid or borrower-paid, the proxy test, the 10% bonus limit, the steering safe harbor, NMLS IDs and records.
$49 10 chapters, 41-page PDF + online copy
Flood compliance toolkit
The Flood Compliance Toolkit for Lenders and Loan Staff (12 CFR 339, 2026)
Test a flood file against 12 CFR 339 and the 2022 Interagency Q&As: triggers, the determination, exemptions, the minimum amount, deductibles, escrow, notices, private flood and force placement.
$39 9 chapters, 35-page PDF + online copy
Condo buyer ebook
The Condo Buyer's Mortgage Workbook: Project Approval, HOA Questionnaire and Insurance
Know before the appraisal whether the building can be financed: the 2026 project review rules, the HOA questionnaire line by line, FHA and VA approval, HO-6, assessments and the true monthly cost.
$29 9 chapters, 41-page PDF + online copy
ECOA adverse action toolkit
The ECOA and Regulation B Adverse Action Toolkit for Mortgage Lenders (2026)
Send the right Regulation B notice on time with the real reasons: applications, the 30-day clock, Appendix C forms, counteroffers, the valuations rule, age and income, 25-month records.
$49 10 chapters, 50-page PDF + online copy
$19 is the total you pay: no tax or fee is added at checkout. Payment by Stripe (card or Apple Pay), instant access after payment. Terms of sale and refund policy. Claude Loan is an information publisher, not a lender or advisor; the ebook is not legal or financial advice.