The Reverse Mortgage (HECM) Decision Workbook (2026)
Understand what a HECM really costs, prepare your counseling session, protect a spouse and your heirs, and compare it honestly with the alternatives before anyone asks you to sign
Guaranteed as described, or refunded in full, and the wrong title switched within 7 days. Refund policy
For $75 more: The Claude Loan Library: Every Workbook and Ebook, 16 titles, $6.19 per title.
Secure checkout by Stripe (card or Apple Pay). Refund policy
Questions: mail@noreply.claude-loan.com
- 10chapters
- 42checklist items
- 16tables
Checked before every release
Every rule is cited by section to an official source you can open (how titles are checked, corrections)
- 68automated testsrun at every release: prices, links, pages and data checked before publication.
- ✓Rules cited by sectionevery rule quoted with its section (HUD, CFPB) so you can check it.
- October 21, 2026editiondate of the current edition; rules and annual limits are updated when they change, and corrections are dated.
Built from the rules and data of HUD, CFPB.
Who it is for
- Homeowners aged 62 or older, and their adult children, who are considering a reverse mortgage and want to understand it before the required counseling session
- Spouses who are not 62 yet, or not on the title, and need to know what happens to them
- Heirs of a borrower who has died or moved to long-term care and who need to know their options and deadlines
What it is not: it does not replace the HUD-required counseling session, which is free or low cost from a HUD-approved counselor; it is not legal, tax or benefits advice and does not recommend a lender, a loan or a decision.
In pictures
Illustrative photos, published by their authors under free licenses. They do not show our team, our readers or any loan.
Free guides, this ebook or the library
Our free guides explain the rules. The paid titles are the working copies: worksheets and checklists you fill in for your own loan, each citing the official rule.
Free guides
$0
our articles and your free state guide (PDF)
- ✓The rules explained, official sources cited
- —Worksheets you fill in for your own loan
- —42 checklist items
- —16 worksheets and reference tables
- —24-page PDF to print, plus an online copy
- —All 13 ebooks and the complete home loan kit
Reverse mortgage ebook
$24
paid once
- ✓The rules explained, official sources cited
- ✓Worksheets you fill in for your own loan
- ✓42 checklist items
- ✓16 worksheets and reference tables
- ✓24-page PDF to print, plus an online copy
- —All 13 ebooks and the complete home loan kit
The Claude Loan Library: Every Workbook and Ebook
$99
16 titles; $431 bought one by one
- ✓The rules explained, official sources cited
- ✓Worksheets you fill in for your own loan
- ✓42 checklist items
- ✓16 worksheets and reference tables
- ✓24-page PDF to print, plus an online copy
- ✓All 13 ebooks and the complete home loan kit
Guaranteed as described, or refunded in full
What is inside
- How a HECM works, and the 2026 numbers free below
- Every cost, up front and over time
- Choosing how to receive the money
- The obligations that can make the loan due
- Spouses, co-owners and others living in the home
- What heirs can do, and the deadlines
- Reading your disclosures and preparing the counseling session
- Three scenarios, priced over 15 years
- Planning the exit: moving, care, selling and family
- Alternatives, taxes and benefits, and the scams to avoid
Included in the paid chapters: 42 checklist items and 14 worksheets or reference tables, each citing the official rule it relies on.
Introduction
A reverse mortgage lets a homeowner aged 62 or older borrow against the home's value without monthly mortgage payments. The loan is repaid later, usually when the last borrower leaves the home or dies. Almost all reverse mortgages in the United States are Home Equity Conversion Mortgages (HECMs), insured by the Federal Housing Administration under rules set by Congress and HUD.
A HECM can be a sound tool, and it can also be a costly mistake: the balance grows every month, the fees are high at the start, the borrower keeps paying property taxes, insurance and upkeep, and the rules for a younger spouse and for heirs are strict. Federal law requires a counseling session with a HUD-approved counselor before you apply, precisely because the decision is complex.
This workbook prepares you for that session and for the decision. It explains the 2026 rules and limits, every fee, the payout choices, how the balance and the line of credit grow, the obligations that can make the loan due, the protections for a non-borrowing spouse, what heirs can do, how to read the loan cost disclosure, and the alternatives you should price first. Each chapter ends with a worksheet or checklist. If you are an adult child helping a parent, fill it in together.
The rules quoted are those in force in October 2026: section 255 of the National Housing Act (12 U.S.C. 1715z-20), HUD's HECM regulation (24 CFR part 206), HUD Mortgagee Letters (including Mortgagee Letter 2025-22 for the 2026 limit and Mortgagee Letter 2017-12 for mortgage insurance premiums), and Regulation Z's reverse mortgage rules (12 CFR 1026.33).
Chapter 1: How a HECM works, and the 2026 numbers
The basic mechanics
- The youngest borrower must be 62 or older at closing (24 CFR 206.33), and the home must be the borrowers' principal residence.
- The lender calculates a principal limit: the most you can borrow. It depends on the age of the youngest borrower (or eligible non-borrowing spouse), the expected interest rate, and the home's value up to the national limit.
- Existing mortgages and liens must be paid off from the principal limit (or with your own money) at closing.
- What is left can be taken as a lump sum (fixed-rate HECMs only), monthly payments, a line of credit, or a combination (24 CFR 206.19).
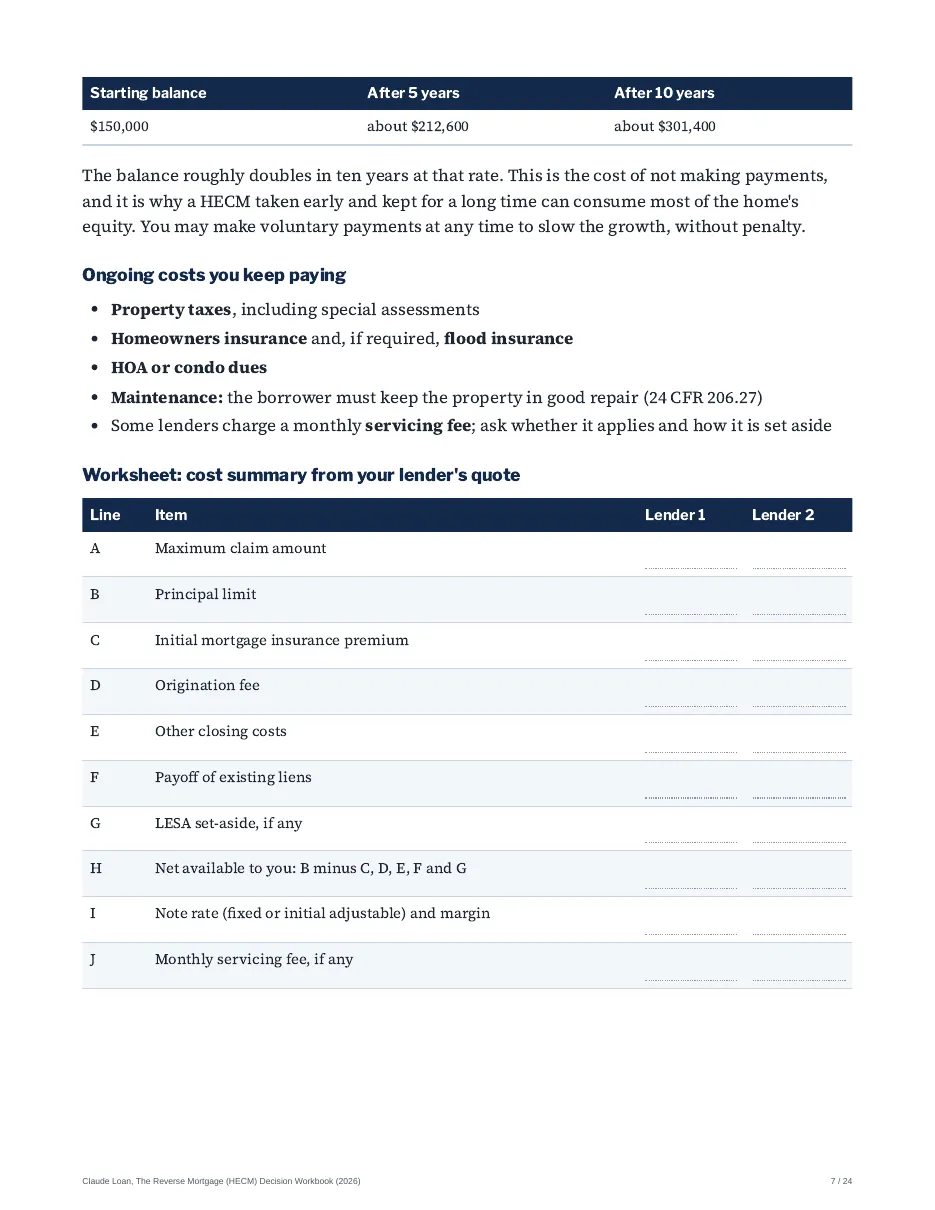
- Interest and mortgage insurance are added to the balance every month. You make no required monthly principal and interest payment, but you can pay voluntarily.
- The loan becomes due when the last borrower dies, sells, or no longer lives in the home, or breaks an obligation (chapter 4).
- The HECM is non-recourse: neither you nor your heirs owe more than the home is worth when it is sold; FHA's insurance covers any shortfall (24 CFR 206.27(b)(8)).
The 2026 numbers
| Item | 2026 figure | Source |
|---|---|---|
| Maximum claim amount (the most home value the HECM counts) | $1,249,125, nationwide, for case numbers assigned January 1 to December 31, 2026 | HUD Mortgagee Letter 2025-22 |
| Minimum age of youngest borrower | 62 | 24 CFR 206.33 |
| Initial mortgage insurance premium | 2% of the maximum claim amount | HUD Mortgagee Letter 2017-12 |
| Annual mortgage insurance premium | 0.5% of the outstanding balance, accruing monthly | HUD Mortgagee Letter 2017-12 |
| Origination fee cap | The greater of $2,500 or 2% of the first $200,000 of the maximum claim amount plus 1% of the rest, never more than $6,000 | 24 CFR 206.31(a)(1) |
| First-year disbursement limit (adjustable-rate HECMs) | Generally 60% of the principal limit, or mandatory obligations plus 10% of the principal limit if higher | 24 CFR 206.25(a) and HUD notice |
The maximum claim amount is the lesser of the home's appraised value and the national limit. A $400,000 home has a maximum claim amount of $400,000; a $1,500,000 home has one of $1,249,125.
Worksheet: is a HECM even possible for you?
| Question | Your answer |
|---|---|
| Age of each owner and each spouse today | |
| Is the home your principal residence, and will it remain so? | |
| Estimated home value | |
| Current mortgage and other liens on the home (payoff amounts) | |
| Property taxes and homeowners insurance per year; HOA dues; flood insurance if any | |
| Are taxes, insurance and dues paid on time today? Any arrears? | |
| Condition of the house: repairs FHA's appraiser may require? | |
| Property type: single-family, 2-to-4 units you live in, FHA-approved condo, manufactured home meeting FHA standards | |
| Any federal debt in default (student loans, taxes)? | |
| Who else lives in the home: spouse not on title, adult child, caregiver |
Proprietary reverse mortgages
Some lenders offer private ("proprietary" or "jumbo") reverse mortgages, not insured by FHA, for homes worth more than the HECM limit or for property types FHA does not accept. They are not bound by the HECM rules in this workbook (limits, fee caps, spouse protections, the 95% rule for heirs). If you are offered one, ask for each of those protections in writing and compare.
Checkout by Stripe
Pay by card on Stripe’s secure page. Your card details never reach our servers.
Instant access
Your ebook opens right after payment, to bookmark, print or save as a PDF. A payment receipt is emailed to you.
One price, paid once
The price shown is the total in US dollars. No subscription, nothing charged later. Refund policy.
Sources you can check
3 links to official sources (HUD, CFPB). An information publisher, not a lender, broker or advisor; not legal or financial advice. Terms of sale.
Frequently asked questions
What exactly do I receive?
Right after payment you land on your ebook page: the full text online, and a button to download the PDF (24 pages, US Letter, printable). Bookmark the page: the link stays valid and always shows the latest version. Your invoice is emailed to you.
Is it up to date for 2026?
Yes. Every rule is quoted as in force in October 2026, with its section number (CFR, HUD, FEMA, Fannie Mae or state rule) so you can check it yourself. When a rule or an annual limit changes, we update the online copy and the PDF.
Is the payment secure, and is it a subscription?
You pay once on Stripe’s secure checkout, by card or Apple Pay; your card details go to Stripe and never reach us. There is no subscription and nothing is charged later.
Who publishes the ebook?
Claude Loan, an information publisher: not a lender, broker, insurance agent, law firm or advisor, with no NMLS license. The ebook explains the official rules and gives you worksheets; your lender, insurance agent, a HUD-approved housing counselor or an attorney give the answers that apply to you.
What is the guarantee?
The ebook is guaranteed as described: if it does not open or contains an error, we fix it, and if we cannot, we refund you in full. Bought the wrong title by mistake? Write within 7 days and we switch it. A duplicate payment is always refunded. See the refund policy in the terms of sale.
Our other ebooks
Flood insurance ebook
The Flood Insurance Workbook for Home Buyers and Condo Owners (2026)
What your lender must require, what an NFIP or private policy really pays, the condo RCBAP gaps, and how to lower the premium before you sign.
$19 9 chapters, 28-page PDF + online copy
Title insurance ebook
The Owner's Title Insurance Guide for Home Buyers (2026)
Decide on the owner’s policy with real numbers: state rates, the Loan Estimate math, who pays, the commitment line by line, endorsements and claims.
$19 8 chapters, 22-page PDF + online copy
Construction loan ebook
The Construction and Renovation Loan Workbook (2026)
One-time or two-time close, FHA 203(k) 2026 rules, HomeStyle, USDA combination loans, then budgets, builder checks, draw schedules and conversion.
$24 10 chapters, 27-page PDF + online copy
Compliance study guide
The Mortgage Compliance Study Guide (2026): ECOA, TRID, RESPA, SAFE Act and More
One-page rule summaries with the 2026 thresholds and more than 100 original practice questions, each answered with the exact CFR section.
$39 10 chapters, 32-page PDF + online copy
Self-employed ebook
The Self-Employed Mortgage Income Workbook (2026)
Run the Form 1084 cash flow on your own returns: Schedule C, K-1s, S corps, the liquidity test, under two years, declining income and business funds.
$24 11 chapters, 34-page PDF + online copy
SCRA ebook
The SCRA and Military Homeowner Workbook (2026)
Claim the 6% cap, stop a foreclosure without a court order, end a lease on orders, then keep, rent or sell the house after a PCS, with letters and trackers.
$19 10 chapters, 31-page PDF + online copy
Low appraisal ebook
The Low Appraisal and Appraisal Gap Playbook (2026)
Read the appraisal like an underwriter, file a reconsideration of value that gets read, and close an appraisal gap with numbers, not panic.
$19 10 chapters, 28-page PDF + online copy
Jumbo loan ebook
The Jumbo and High-Balance Loan Workbook (2026)
Find your county’s 2026 limit, see what changes between standard, high-balance and jumbo loans, and price staying under the line with your own numbers.
$29 8 chapters, 28-page PDF + online copy
LO compensation handbook
The Loan Originator Compensation and Conduct Handbook (12 CFR 1026.36, 2026)
Audit a pay plan against 12 CFR 1026.36: lender-paid or borrower-paid, the proxy test, the 10% bonus limit, the steering safe harbor, NMLS IDs and records.
$49 10 chapters, 41-page PDF + online copy
Flood compliance toolkit
The Flood Compliance Toolkit for Lenders and Loan Staff (12 CFR 339, 2026)
Test a flood file against 12 CFR 339 and the 2022 Interagency Q&As: triggers, the determination, exemptions, the minimum amount, deductibles, escrow, notices, private flood and force placement.
$39 9 chapters, 35-page PDF + online copy
Condo buyer ebook
The Condo Buyer's Mortgage Workbook: Project Approval, HOA Questionnaire and Insurance
Know before the appraisal whether the building can be financed: the 2026 project review rules, the HOA questionnaire line by line, FHA and VA approval, HO-6, assessments and the true monthly cost.
$29 9 chapters, 41-page PDF + online copy
ECOA adverse action toolkit
The ECOA and Regulation B Adverse Action Toolkit for Mortgage Lenders (2026)
Send the right Regulation B notice on time with the real reasons: applications, the 30-day clock, Appendix C forms, counteroffers, the valuations rule, age and income, 25-month records.
$49 10 chapters, 50-page PDF + online copy
$24 is the total you pay: no tax or fee is added at checkout. Payment by Stripe (card or Apple Pay), instant access after payment. Terms of sale and refund policy. Claude Loan is an information publisher, not a lender or advisor; the ebook is not legal or financial advice.